India’s 10 Core Economic Engines: An Empirical Breakdown of Growth, Jobs, Trade, and FDI
India’s real GDP growth continues to outpace major peer economies, expanding in the 7.0% to 7.4% corridor. The broader macro story, however, lies in how capital, employment, and global trade are distributed beneath the headline figure. While the services sector still generates over half of national Gross Value Added (GVA) and draws the bulk of foreign equity, industrial policy interventions and infrastructure outlays have started shifting the dynamics of job creation and merchandise exports.
The operational realities, trade balances, employment metrics, and foreign investment flows across India’s 10 primary economic sectors are detailed below.
| # | Sector | Annual Growth Rate (GVA / Output) | Direct & Indirect Employment | Export / Import Dynamic | FDI Share & Inflow Trend |
| 1 | Financial Services & Banking | 10%–12% GVA growth (13%–15% credit growth) | ~8.5–9.5 million [Formal / BFSI] | High service export surplus (Fintech / Cross-border processing) | Major recipient; accounts for 14%–16% of cumulative equity FDI |
| 2 | IT & BPM | 7%–9% CAGR [Services GVA ~9%] | ~5.6 million direct; ~18 million indirect | Net exporter: ~$200B+ net surplus; negligible imports | Dominant FDI destination (~22%–25% with Hardware/Software) |
| 3 | Agriculture & Allied | 3.5%–4.5% GVA (Allied sectors 5%–6%) | ~240–250 million (~44%–46% of workforce) | Net exporter: ~$50B+ exports; major imports in vegetable oils/pulses | Negligible FDI equity (<1%); primarily routed to food processing |
| 4 | Automobiles & Auto Components | 9%–11% Volume/Value growth | ~30–35 million direct and indirect | Balanced: Strong commercial/2W exports (~$21B+); capital component imports | Consistent draw (~5%–6% of total FDI); heavy EV/battery inflows |
| 5 | Pharmaceuticals & Healthcare | 9%–11% Industry CAGR | ~4.5–5 million (Pharma manufacturing + Healthcare) | Net exporter: ~$28B+ pharma exports; API/Medical tech import reliant | ~3%–4% of FDI; focused on greenfield plants and domestic hospitals |
| 6 | FMCG & Consumer Goods | 7.5%–9.5% Revenue growth | ~25–30 million (Factory, retail, distribution) | Modest export footprint (~$4B–$6B); imported packaging/raw fats | Attracts steady FDI in single-brand retail, processed foods, and personal care |
| 7 | Energy, Power & Renewables | 7%–8% Power gen; >14% Renewables | ~3–4 million (Thermal, transmission, solar installation) | Net importer: Heavy crude and solar wafer imports; power exports to neighbors | Rapidly accelerating FDI; accounts for 4%–5% of recent clean-tech inflows |
| 8 | Infrastructure & Construction | 8.5%–10% GVA growth | ~70–75 million (Second-largest national employer) | Services/logistics exporter; import-heavy in specialized tunneling/rail tech | Large recipient via Infrastructure Investment Trusts (InvITs) and sovereign funds |
| 9 | Real Estate & Urban Spaces | 11%–13% Market size expansion | ~18–20 million (Skilled, corporate, civil, architectural) | Domestic market; high imports of premium building fittings/elevators | Strong institutional FDI via private equity and Listed REITs (~4%–5%) |
| 10 | Telecommunications & DPI | 8%–10% Data/Network revenue | ~4–4.5 million direct and indirect | Service exporter via digital rails; hardware/semiconductor import reliant | ~6% of cumulative FDI; consolidation into a tight private three-player market |
India’s 10 Core Economic Engines: An Empirical Breakdown of Growth, Jobs, Trade, and FDI
India’s real GDP growth continues to outpace major peer economies, expanding in the 7.0% to 7.4% corridor. The broader macro story, however, lies in how capital, employment, and global trade are distributed beneath the headline figure. While the services sector still generates over half of national Gross Value Added (GVA) and draws the bulk of foreign equity, industrial policy interventions and infrastructure outlays have started shifting the dynamics of job creation and merchandise exports.
The operational realities, trade balances, employment metrics, and foreign investment flows across India’s 10 primary economic sectors are detailed below.
Comparative Sector Performance Dashboard
| # | Sector | Annual Growth Rate (GVA / Output) | Direct & Indirect Employment | Export / Import Dynamic | FDI Share & Inflow Trend |
| 1 | Financial Services & Banking | 10%–12% GVA growth (13%–15% credit growth) | ~8.5–9.5 million [Formal / BFSI] | High service export surplus (Fintech / Cross-border processing) | Major recipient; accounts for 14%–16% of cumulative equity FDI |
| 2 | IT & BPM | 7%–9% CAGR [Services GVA ~9%] | ~5.6 million direct; ~18 million indirect | Net exporter: ~$200B+ net surplus; negligible imports | Dominant FDI destination (~22%–25% with Hardware/Software) |
| 3 | Agriculture & Allied | 3.5%–4.5% GVA (Allied sectors 5%–6%) | ~240–250 million (~44%–46% of workforce) | Net exporter: ~$50B+ exports; major imports in vegetable oils/pulses | Negligible FDI equity (<1%); primarily routed to food processing |
| 4 | Automobiles & Auto Components | 9%–11% Volume/Value growth | ~30–35 million direct and indirect | Balanced: Strong commercial/2W exports (~$21B+); capital component imports | Consistent draw (~5%–6% of total FDI); heavy EV/battery inflows |
| 5 | Pharmaceuticals & Healthcare | 9%–11% Industry CAGR | ~4.5–5 million (Pharma manufacturing + Healthcare) | Net exporter: ~$28B+ pharma exports; API/Medical tech import reliant | ~3%–4% of FDI; focused on greenfield plants and domestic hospitals |
| 6 | FMCG & Consumer Goods | 7.5%–9.5% Revenue growth | ~25–30 million (Factory, retail, distribution) | Modest export footprint (~$4B–$6B); imported packaging/raw fats | Attracts steady FDI in single-brand retail, processed foods, and personal care |
| 7 | Energy, Power & Renewables | 7%–8% Power gen; >14% Renewables | ~3–4 million (Thermal, transmission, solar installation) | Net importer: Heavy crude and solar wafer imports; power exports to neighbors | Rapidly accelerating FDI; accounts for 4%–5% of recent clean-tech inflows |
| 8 | Infrastructure & Construction | 8.5%–10% GVA growth | ~70–75 million (Second-largest national employer) | Services/logistics exporter; import-heavy in specialized tunneling/rail tech | Large recipient via Infrastructure Investment Trusts (InvITs) and sovereign funds |
| 9 | Real Estate & Urban Spaces | 11%–13% Market size expansion | ~18–20 million (Skilled, corporate, civil, architectural) | Domestic market; high imports of premium building fittings/elevators | Strong institutional FDI via private equity and Listed REITs (~4%–5%) |
| 10 | Telecommunications & DPI | 8%–10% Data/Network revenue | ~4–4.5 million direct and indirect | Service exporter via digital rails; hardware/semiconductor import reliant | ~6% of cumulative FDI; consolidation into a tight private three-player market |
Detailed Sectoral Breakdowns
1. Financial Services & Banking
- Overview: The sector acts as the primary transmission mechanism for domestic liquidity. Balance sheets have undergone a clean-up cycle, with system-wide Gross Non-Performing Assets (GNPAs) dropping near multi-decade lows of 2.2%.
- Job Creation: High demand for skilled white-collar talent across risk management, private credit underwriting, actuarial science, and digital collection mechanisms.
- Trade Profile: Net positive on services trade. Domestic banks primarily intermediate domestic savings, while expanding Global Capability Centers (GCCs) export quantitative and treasury analytics abroad.
- FDI & Capital Flows: Continuously ranks as one of the top three destinations for foreign capital, particularly through foreign institutional investor (FII) equity holdings and strategic investments in private non-banking financial companies (NBFCs).
2. Information Technology (IT) & Business Process Management (BPM)
- Overview: Moving past commoditized system maintenance, the Indian IT complex is re-allocating capital toward enterprise artificial intelligence integration, hyperscale cloud engineering, and proprietary enterprise software.
- Job Creation: Employs over 5.5 million direct software engineers, though hiring volumes have pivoted away from mass campus intakes toward specialized lateral capabilities.
- Trade Profile: India’s primary trade balancer. While merchandise trade frequently runs a deficit, IT and software services generated a massive surplus, keeping the Current Account Deficit (CAD) within manageable bounds.
- FDI & Capital Flows: Consistently captures the largest single slice of annual FDI equity inflows when grouped with computer hardware. Global technology conglomerates maintain their largest overseas development campuses within southern and western Indian tech corridors.
3. Agriculture & Allied Industries
- Overview: While contributing roughly 16%–18% of GVA, the sector still supports nearly half of India’s civilian population. Growth is largely led not by traditional grain crops, but by allied sub-sectors like dairy, fisheries, poultry, and high-density horticulture.
- Job Creation: The single largest employer nationwide, though experiencing structural disguised unemployment. Policy focuses on absorbing excess agricultural labor into rural agro-processing and light manufacturing.
- Trade Profile: Substantial net exporter of rice, marine products (shrimp), spices, and sugar. Conversely, India remains structurally import-dependent on edible oils (palm, soybean) and pulses, which creates domestic food inflation vulnerabilities.
- FDI & Capital Flows: Direct farm cultivation remains closed to foreign equity. FDI is concentrated entirely in downstream supply chains—cold storage, contract processing, and automated warehousing.
4. Automobiles & Auto Components
- Overview: India has solidified its position as the world’s third-largest automotive market, underpinned by an indigenous supply chain of tier-1 and tier-2 parts makers.
- Job Creation: A critical engine for semi-skilled blue-collar employment, vocational engineering, and assembly line operators across established hubs in Tamil Nadu, Maharashtra, and the National Capital Region (NCR).
- Trade Profile: High-volume exporter of compact passenger vehicles, tractors, two-wheelers, and precision engine blocks to Africa, Latin America, and Southeast Asia. Key import dependencies remain lithium-ion cells and advanced electronic microcontrollers.
- FDI & Capital Flows: 100% automatic route FDI has historically brought in global original equipment manufacturers (OEMs). Recent inflows prioritize joint ventures in electric drive units, battery assembly, and local automotive software.
5. Pharmaceuticals & Healthcare
- Overview: Widely recognized as the volume supplier of global generics and vaccines, the sector is attempting a transition into higher-margin complex formulations, biosimilars, and active pharmaceutical ingredient (API) synthesis.
- Job Creation: Generates a mix of high-skill research roles (formulation scientists, regulatory analysts) and large-scale medical operations teams across clinical hospital chains.
- Trade Profile: Generates a consistent trade surplus exceeding $28 billion annually. A primary vulnerability remains its historical reliance on China for basic raw chemicals, Key Starting Materials (KSMs), and bulk APIs.
- FDI & Capital Flows: Greenfield projects operate under the 100% automatic route, whereas brownfield buyouts allow up to 74% automatically. Private equity has heavily favored investments in regional hospital networks and specialty diagnostic lab chains.
6. Fast-Moving Consumer Goods (FMCG)
- Overview: Dominated by a bifurcated demand structure: urban centers shifting toward premium, wellness, and quick-commerce delivery, while rural volume uptake depends on harvest cycles and monsoon distribution.
- Job Creation: Massive driver of informal and semi-formal employment, particularly across last-mile transport, retail distribution, inventory management, and regional packaging centers.
- Trade Profile: Largely an inwardly focused domestic consumption market. Imports center on crude palm oil and agricultural inputs; exports are restricted to branded ethnic foods and packaged personal hygiene products to the Indian diaspora.
- FDI & Capital Flows: Multinational parent entities hold significant controlling equity stakes across listed domestic arms, using regular reinvestment of internal accruals rather than primary foreign inflows.
7. Energy, Power & Renewables
- Overview: The central dynamic is balancing baseline energy security (dominated by coal-fired generation) against one of the world’s most aggressive utility-scale solar and wind build-outs.
- Job Creation: High short-term engineering and site construction employment for utility projects; long-term asset management tends to be automated with low ongoing headcounts.
- Trade Profile: The primary driver of the nation’s trade deficit via crude petroleum, liquefied natural gas (LNG), and thermal coal. The country also imports a significant portion of its solar cells and raw wafers.
- FDI & Capital Flows: Capital-intensive sector drawing sovereign wealth funds, multilateral climate capital, and overseas pension funds directly into renewable independent power producers (IPPs) and green hydrogen consortiums.
8. Infrastructure & Construction
- Overview: The primary growth catalyst in recent fiscal cycles, driven by direct public capital expenditure allocations aimed at highway building, port modernization, and freight rail corridors.
- Job Creation: The largest absorber of manual and unorganized labor shifting off rural farms, serving as a social safety net during industrial transitions.
- Trade Profile: Net consumer of industrial commodities (domestic and imported steel, asphalt, specialized earthmoving machinery). Cross-border engineering and procurement services are expanding in the Middle East and East Africa.
- FDI & Capital Flows: Channelled primarily through structured financial instruments such as Infrastructure Investment Trusts (InvITs) and bilateral project debt rather than conventional venture-style corporate equity.
9. Real Estate & Urban Development
- Overview: The industry has experienced consolidation following regulatory tightening, which systematically redirected buyer preference away from unorganized regional operators toward well-capitalized, publicly listed developers.
- Job Creation: Extensive employment footprint across civil engineering, master planning, architecture, construction labor, and downstream finishing trades (paints, plumbing, electrical).
- Trade Profile: Almost strictly a domestic non-tradable sector. Indirect import demand includes luxury finishing goods, architectural hardware, and specialized HVAC equipment.
- FDI & Capital Flows: Institutional global funds (e.g., Blackstone, Brookfield, GIC) actively acquire Grade-A commercial commercial office spaces, industrial parks, and logistics warehouses, monetizing these portfolios through public REITs.
10. Telecommunications & Digital Infrastructure
- Overview: A consolidated three-player private market that provides the physical plumbing for the world’s highest average monthly wireless data consumption per subscriber.
- Job Creation: Direct operational employment remains lean due to automated billing and network management. Job creation is indirect, serving as the foundational layer that enables millions of gig-economy drivers, delivery partners, and software developers.
- Trade Profile: Net importer of complex telecommunication equipment, core routing hardware, and base-station semiconductor components, primarily from East Asia and Northern Europe.
- FDI & Capital Flows: Benefited from earlier multi-billion-dollar investments into integrated domestic telecom and tech platforms; ongoing foreign capital enters via automated routes for infrastructure tower sales, telecom gear joint ventures, and enterprise edge computing centers.
 The Growth Arithmetic vs. Ground Realities: India’s Macro Balance Sheet Needs More Than Sectoral Triumphalism
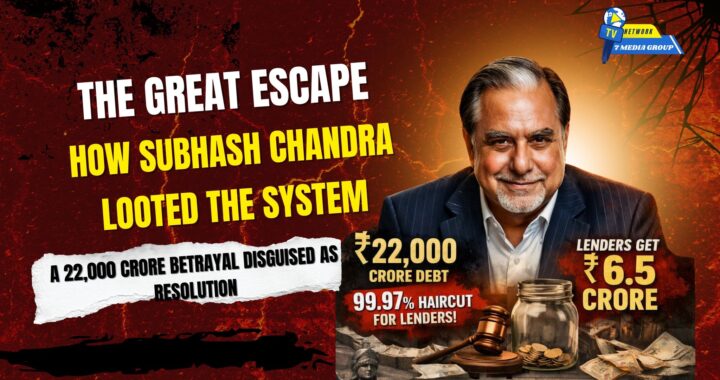 The 3-Paise Settlement: How India’s Financial Architecture Capitulated to Subhash Chandra’s ₹22,000-Crore Default
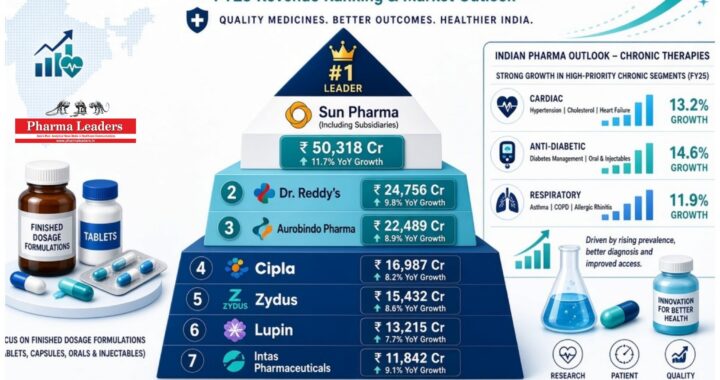 Top 50 Entrepreneurs in Pharmaceutical Industry Powering the Global Medicine Chest
 The Sovereign Architects of India’s Digital Century: Top 50 Women IT Leaders
 4.3 Crore Indians Stranded in Unemployment as Youth Crisis Deepens – Network 7 Research Findings
 Rebuilding Trust: Nandan Nilekani Named Head of High-Powered Task Force to Overhaul India’s Examination System